

Insurance Claims
Earthquake Damage Insurance Claims
Earthquake coverage is commonly provided through a separate policy or endorsement with its own deductible and exclusions. Claims may be disputed over structural causation, pre-existing cracking, repair scope, and whether covered damage exceeds the applicable deductible.


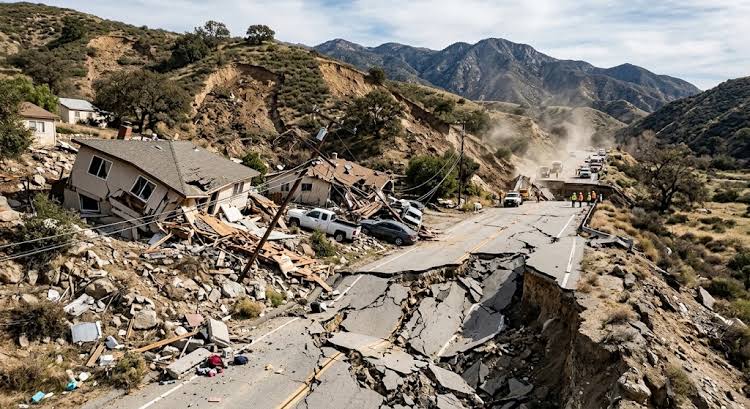
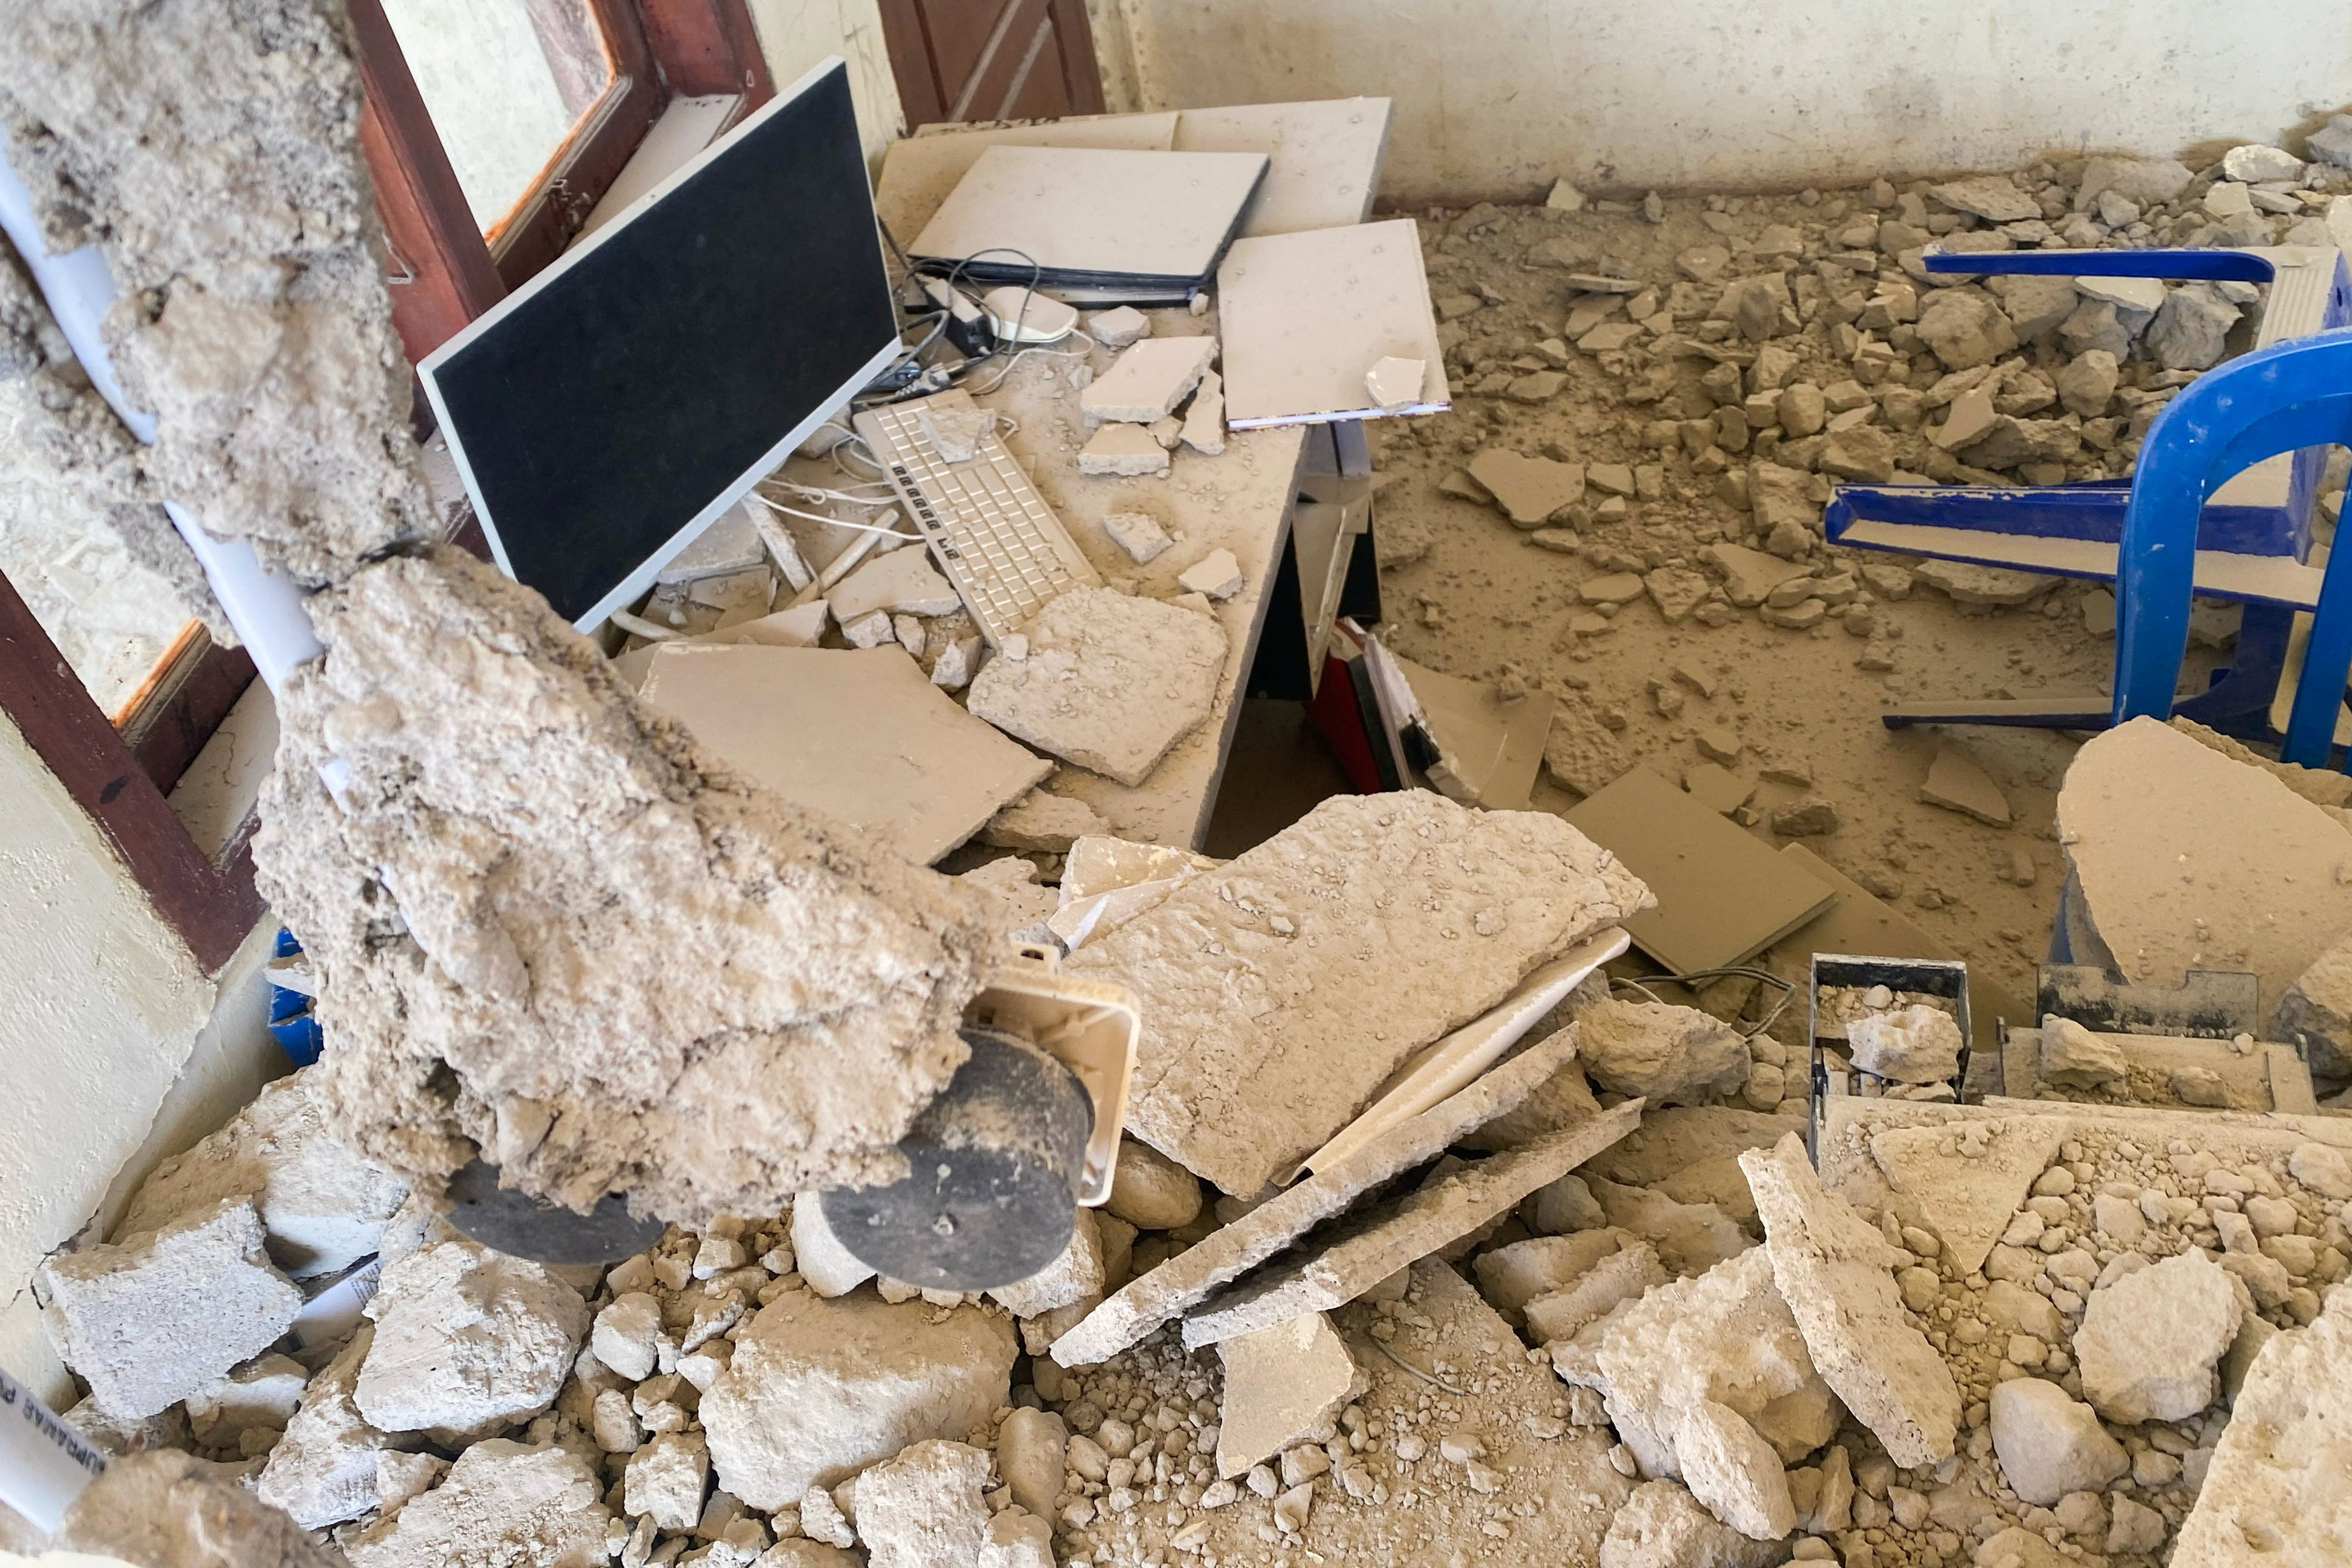

The situation
How earthquake claim disputes are evaluated
Carriers may attribute foundation cracks, settlement, masonry damage, or shifted structural components to soil conditions, age, or earlier movement. Percentage deductibles can be substantial, and a narrow scope may make a covered loss appear to fall below the deductible even when additional earthquake damage exists.

Common obstacles
Why these claims are often disputed
Insurance companies employ experienced adjusters whose role is to limit payouts. Knowing where disputes typically arise gives policyholders a real advantage.


Review specialized earthquake coverage
FDZ Law examines the earthquake policy or endorsement, deductible calculation, exclusions, and carrier correspondence.

Compare pre-loss and post-loss conditions
We organize photographs, maintenance records, inspections, engineering findings, and repair evidence that help show what changed during the seismic event.

Challenge pre-existing damage conclusions
We address unsupported attempts to classify new cracking, displacement, or structural impairment as ordinary settlement or earlier damage.

Present the full covered scope
We pursue recognition and valuation of all supported earthquake damage through negotiation and appropriate legal remedies.

Questions
Earthquake insurance claim FAQs
The information below is general. FDZ Law can review the earthquake coverage, deductible, engineering evidence, and claim decision in a particular matter.
What should I do if my homeowners policy excludes earthquake damage?

Standard homeowners policies often exclude earthquake damage, while a separate earthquake policy or endorsement may provide coverage. FDZ Law can review all available policies and the carrier's decision to determine whether another source of coverage may apply.
How can I verify whether my earthquake deductible was calculated correctly?
Compare the insurer's calculation with the declarations and earthquake endorsement, including the applicable percentage, coverage amount, and any separate deductible by category. FDZ Law can review the calculation if it does not appear to follow the policy.
How can I dispute a claim that foundation cracks existed before the earthquake?
Earlier photographs, inspection reports, maintenance records, prompt post-event measurements, and structural engineering analysis may help distinguish new seismic damage from older settlement. FDZ Law can review that evidence and the insurer's causation position.

Types of claims we handle
Every type of property loss, covered.
We handle every type of covered building and personal property loss that may affect your home or business.


Ready to start the process?
Share the basic details of your situation. The firm will review the information and explain the appropriate next steps.




