

Insurance Claims
Flood Damage Insurance Claims
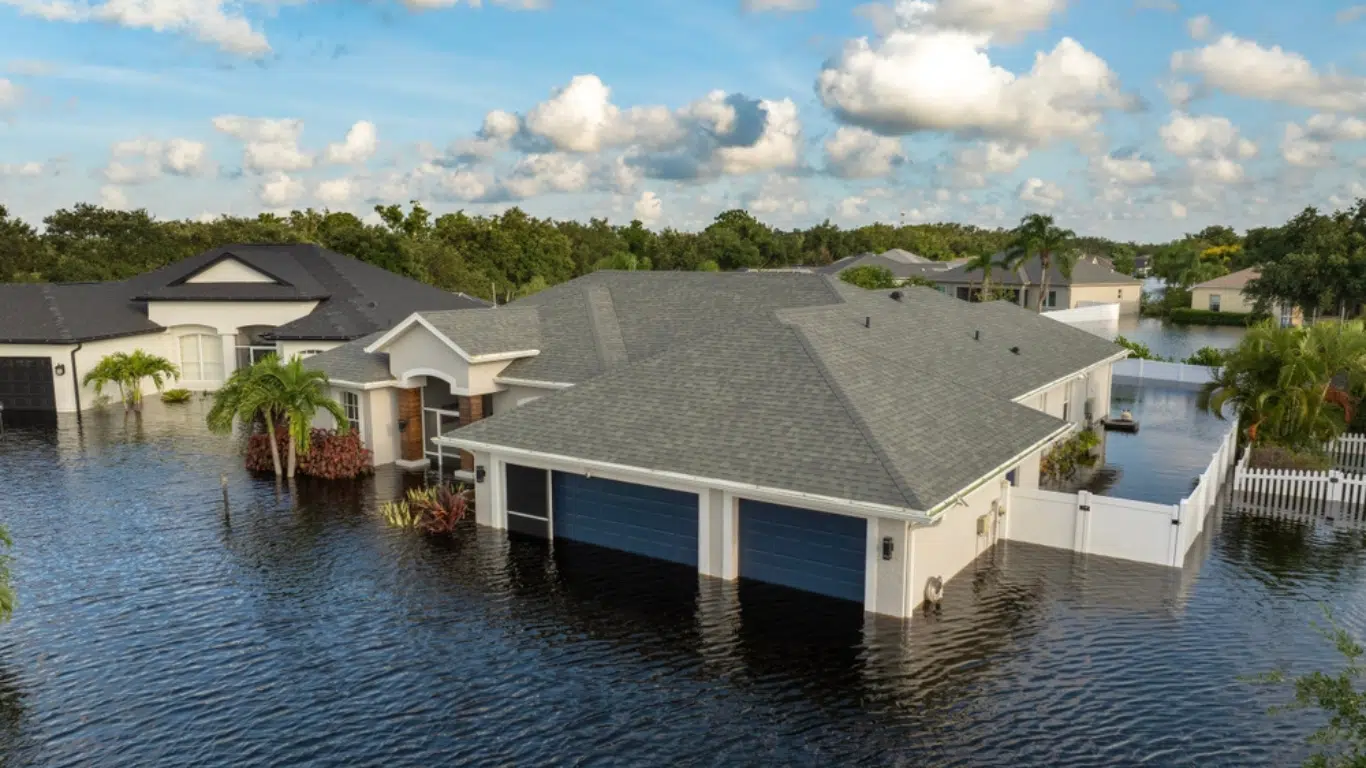
Flood damage may involve a federal or private flood policy together with homeowners or commercial property coverage. When multiple causes affect the same property, policyholders can face conflicting decisions about which insurer should pay for each part of the loss.



The situation
Where flood claim disputes commonly arise
Standard property policies often treat flood differently from wind-driven rain, plumbing failures, or other water events. Disagreements may involve the source of the water, the line between flood and non-flood damage, proof requirements, repair estimates, depreciation, and the limits available under separate policies.

Common obstacles
Why these claims are often disputed
Insurance companies employ experienced adjusters whose role is to limit payouts. Knowing where disputes typically arise gives policyholders a real advantage.


Identify potentially applicable policies
FDZ Law reviews flood, homeowners, commercial, and excess coverage to determine which policies may respond to the reported damage.

Separate competing causes of loss
We organize weather data, inspections, photographs, and expert findings that help distinguish flood damage from wind, rain, or another covered cause.

Present the complete valuation
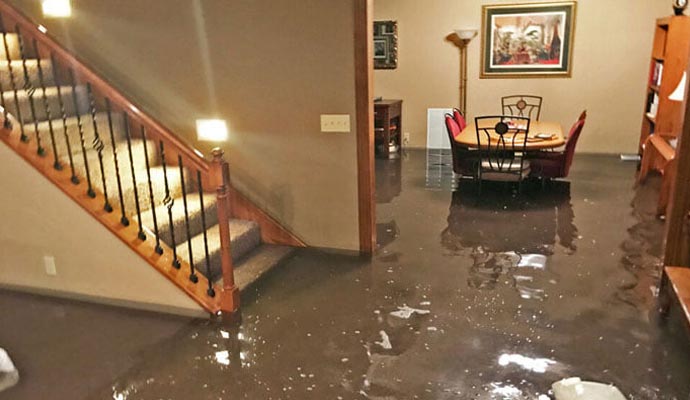
We address omitted rooms, structural components, contents, debris removal, and other documented costs relevant to the covered claim.

Challenge an incomplete determination
When a carrier denies or underpays covered flood damage, we pursue negotiation and available legal remedies based on the governing policy and claim process.

Questions
Flood insurance claim FAQs
These responses are general and coverage varies by policy. FDZ Law can review the policies, cause evidence, and payment history for a particular flood loss.
What options remain if my homeowners insurer denied flood damage?

A standard homeowners policy may exclude certain flood losses, but a separate flood policy or another applicable coverage may respond. FDZ Law can review the available policies, the stated cause of loss, and the insurer's denial to identify possible next steps.
Why might my neighbor's claim be covered when mine is labeled flood damage?
Two claims from the same event may be treated differently because the properties, damage paths, evidence, and policy language are not identical. If you believe your loss was mischaracterized, FDZ Law can review the causation evidence and the insurer's explanation.
Can I challenge the amount paid on a flood insurance claim?
Yes. A policyholder may dispute the scope of covered flood damage or the amount paid, although the applicable procedure and deadlines depend on the policy and program. FDZ Law can review the estimate, payment, and required claim documents.

Types of claims we handle
Every type of property loss, covered.
We handle every type of covered building and personal property loss that may affect your home or business.


Ready to start the process?
Share the basic details of your situation. The firm will review the information and explain the appropriate next steps.




