

Insurance Claims
Mold Damage Insurance Claims
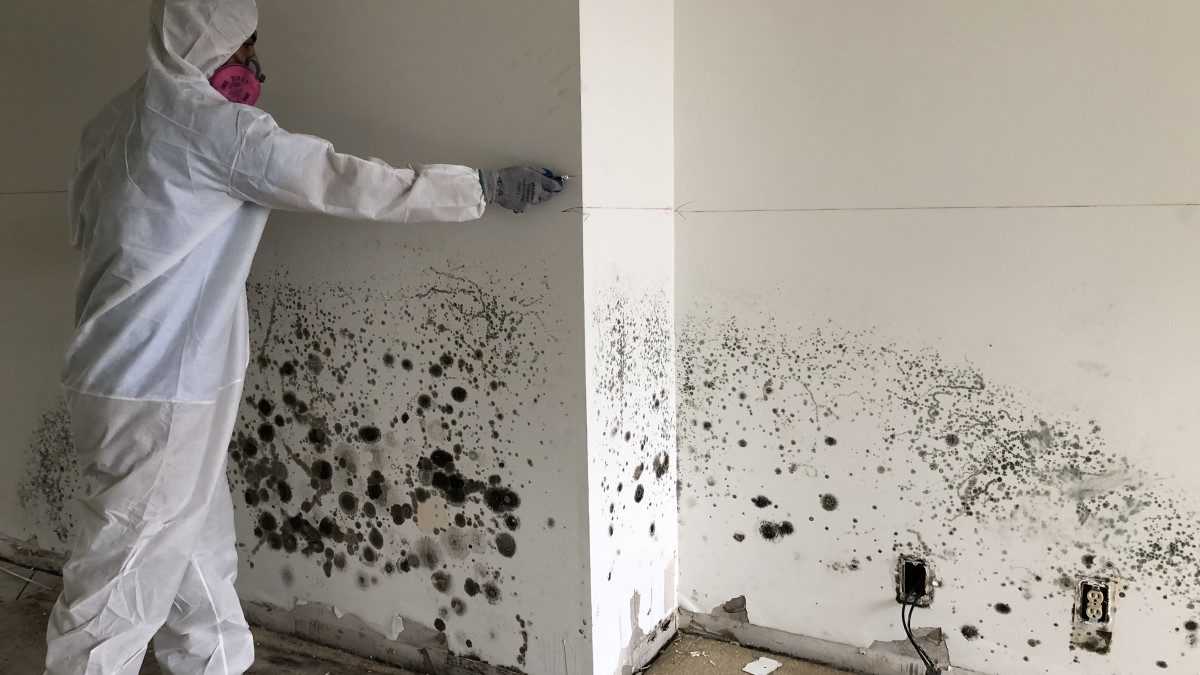
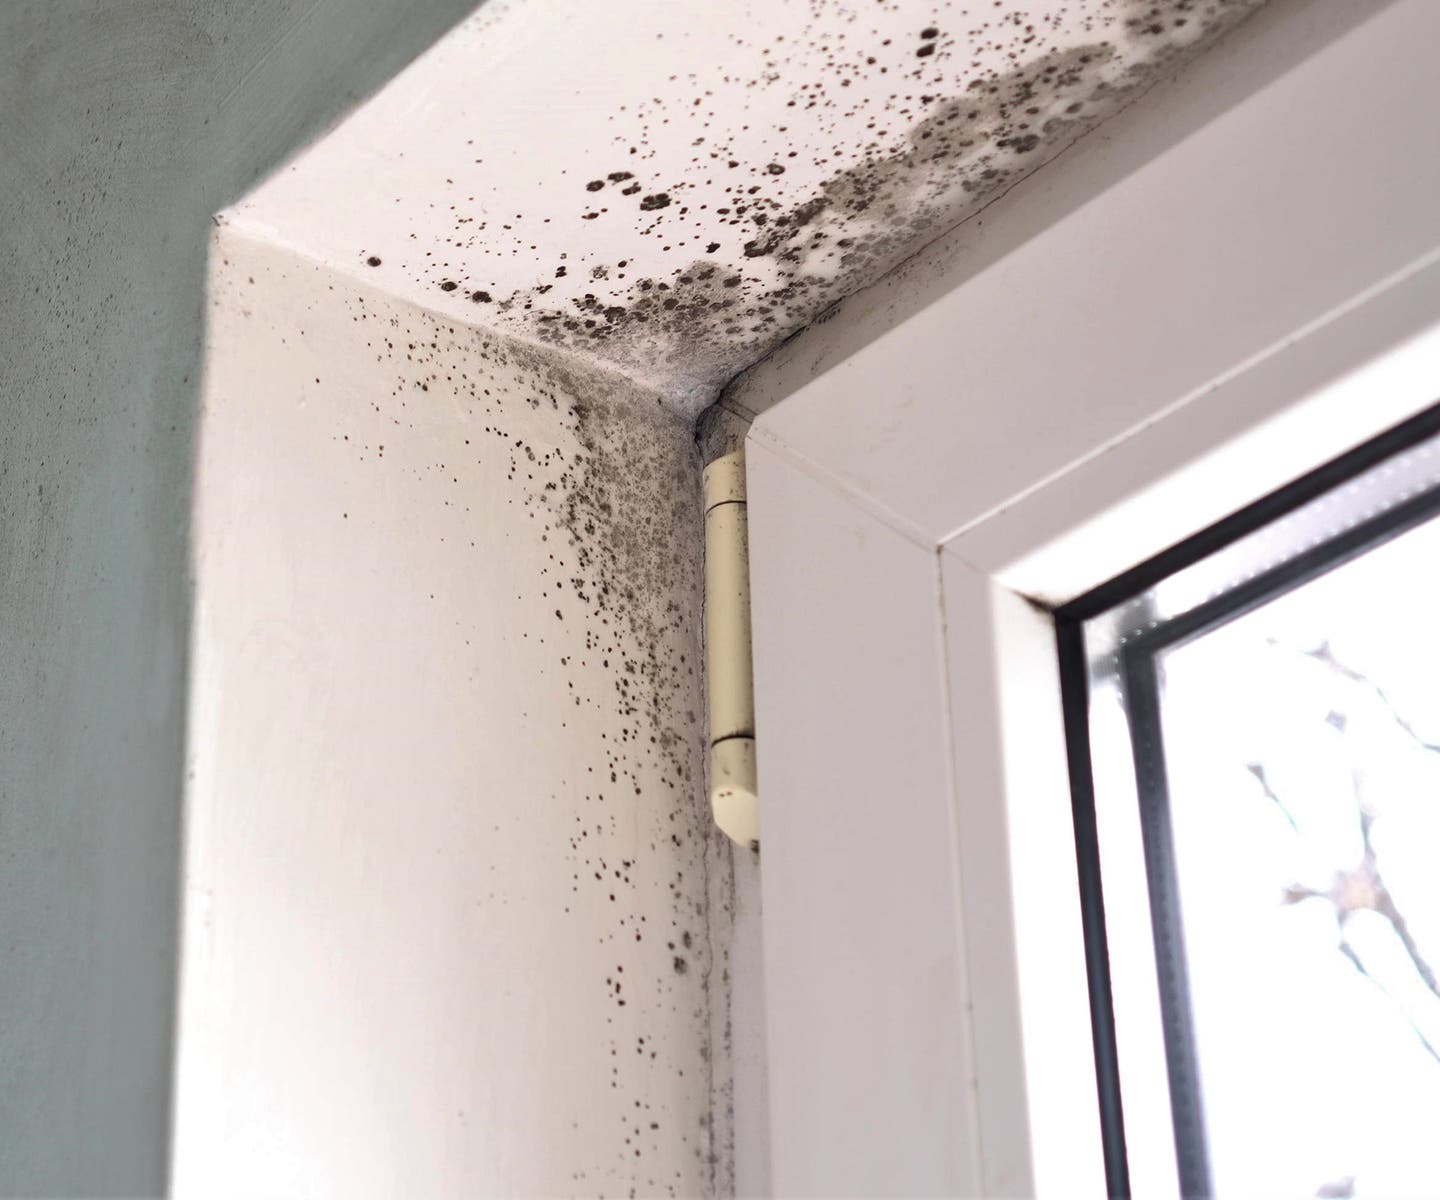
Mold coverage often depends on what caused the moisture, when the condition developed, and which limits or exclusions apply. A carrier may accept the initial water event but dispute the remediation scope or place the resulting mold damage under a much smaller sublimit.



The situation
Why mold claims face special coverage limits
Some policies exclude mold, while others provide limited coverage or treat remediation differently when mold follows a covered water loss. Insurers may argue that growth predates the event, comes from chronic humidity, or is confined to a smaller area than the remediation evidence indicates.

Common obstacles
Why these claims are often disputed
Insurance companies employ experienced adjusters whose role is to limit payouts. Knowing where disputes typically arise gives policyholders a real advantage.


Trace mold to the reported event
FDZ Law reviews the water-loss timeline, inspection records, testing, and policy language to evaluate the claimed source of growth.

Define the remediation scope
We organize evidence concerning affected materials, containment, demolition, cleaning, testing, and reconstruction needed to address the condition.

Examine exclusions and sublimits
We analyze whether the carrier applied the correct provision and whether resulting damage belongs within broader coverage for the underlying event.

Challenge an underpaid mold claim
We negotiate coverage and valuation disputes and assess legal action when the insurer's determination does not match the policy or evidence.

Questions
Mold damage claim FAQs
These answers provide general information. FDZ Law can evaluate the water source, policy limits, and remediation evidence for an individual mold claim.
If mold remediation exceeds my $10,000 sublimit, is recovery automatically capped?

Not necessarily. The answer depends on the policy and how the insurer classifies mold remediation, water-damaged materials, access, testing, and reconstruction. FDZ Law can review whether every disputed cost properly falls within the stated sublimit.
What evidence can challenge a claim that mold existed before the loss?
Water-loss records, moisture history, photographs, mitigation documents, prior inspections, and appropriate environmental findings may help establish when the mold developed. FDZ Law can review whether the available evidence connects it to the reported event.
Can mold coverage apply when the underlying water damage is covered?
It may. Coverage depends on the policy language, the connection between the water event and the mold, and any applicable exclusion, endorsement, or sublimit. FDZ Law can review how those provisions apply to the facts of the claim.

Types of claims we handle
Every type of property loss, covered.
We handle every type of covered building and personal property loss that may affect your home or business.


Ready to start the process?
Share the basic details of your situation. The firm will review the information and explain the appropriate next steps.




