

Insurance Claims
Hurricane Property Damage Claims
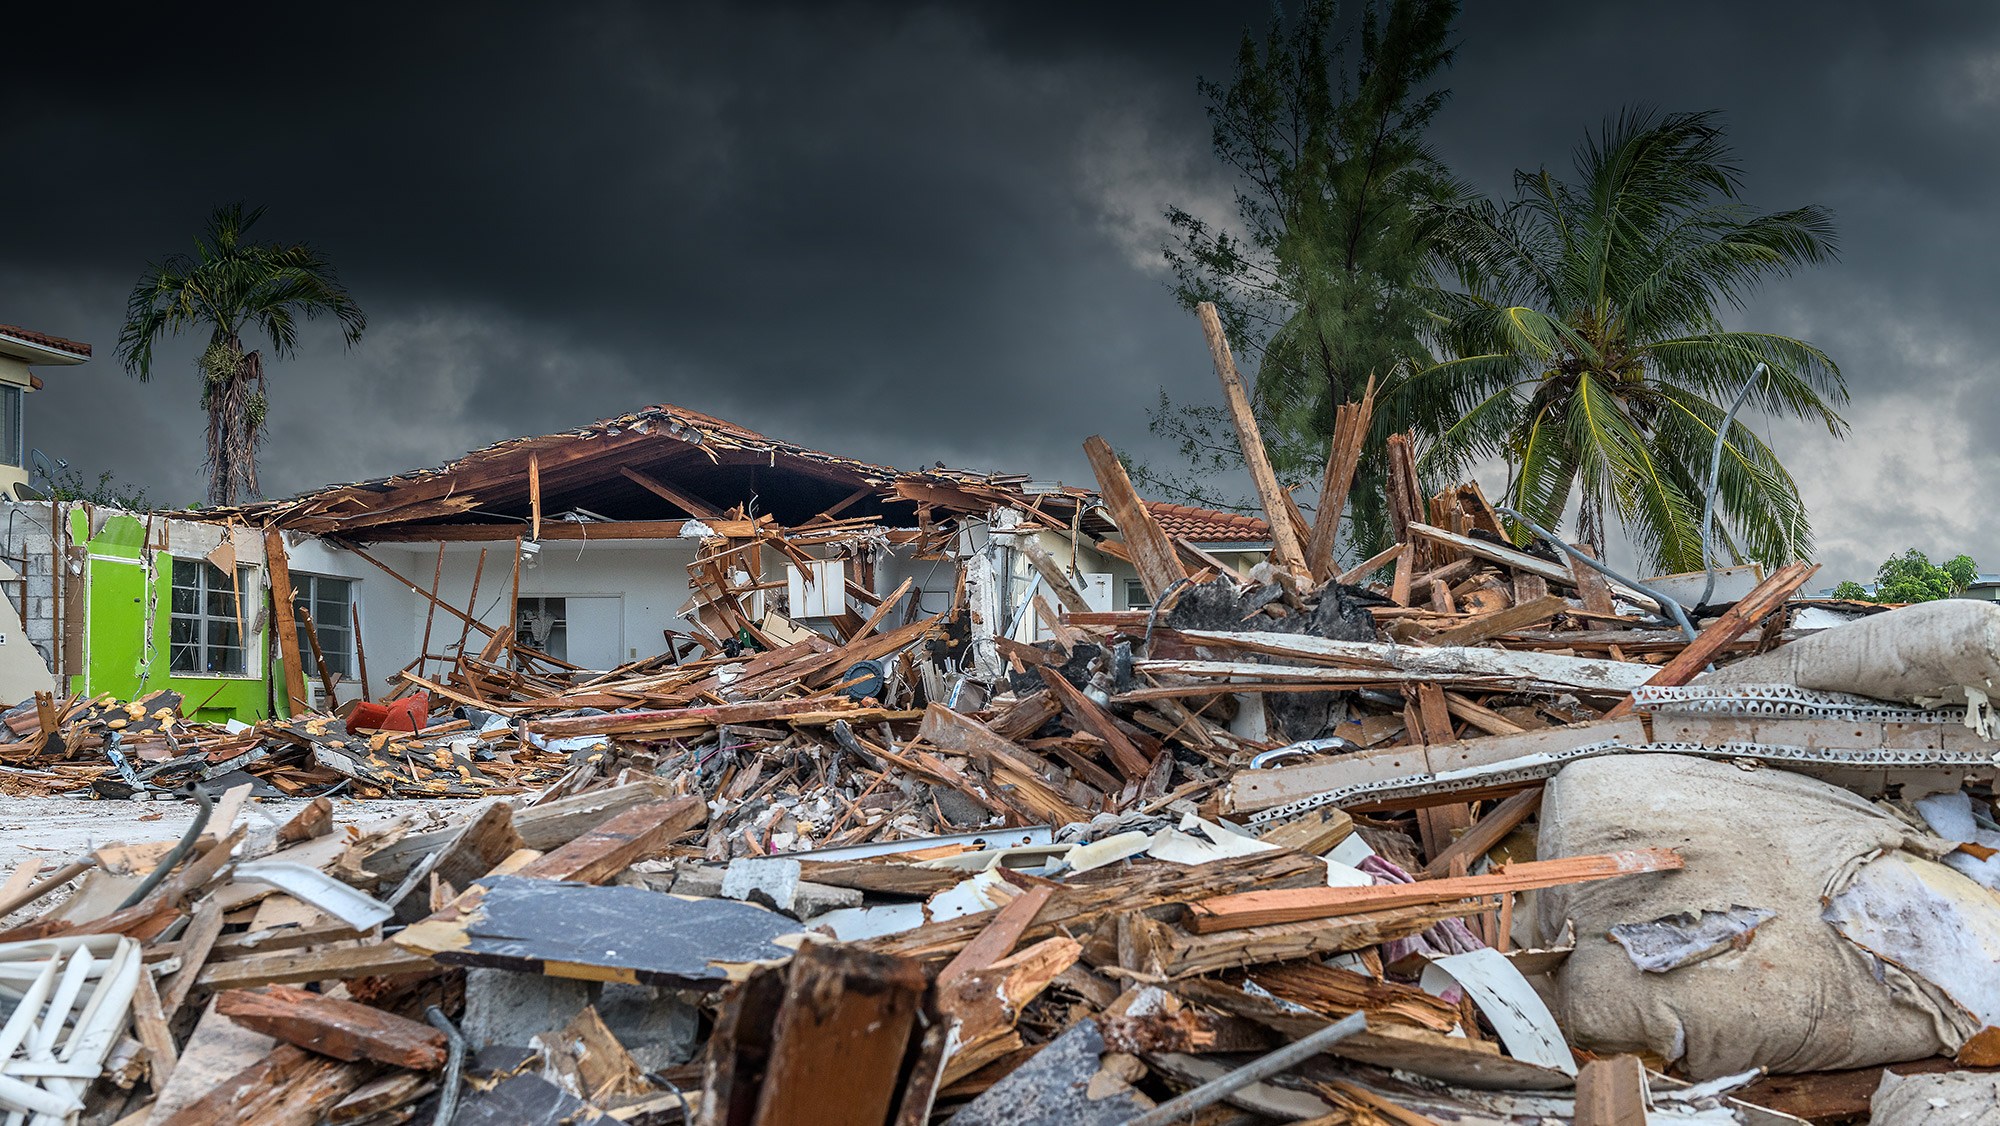
A hurricane can produce wind, wind-driven rain, storm surge, and flooding during the same event. Because those causes may fall under different policies and deductibles, even well-documented losses can lead to overlapping or conflicting coverage decisions.




The situation
Why hurricane claims become especially complex
Homeowners, commercial, wind, and flood insurers may disagree about which force caused specific damage. Percentage-based hurricane deductibles, multiple inspections, emergency repairs, and separate claim requirements can make it difficult to determine whether the combined payments reflect the complete covered loss.

Common obstacles
Why these claims are often disputed
Insurance companies employ experienced adjusters whose role is to limit payouts. Knowing where disputes typically arise gives policyholders a real advantage.


Coordinate all available coverage
FDZ Law reviews each applicable policy, claim number, deductible, and coverage decision as parts of one hurricane loss.

Develop a cause-by-cause record
We organize evidence showing how wind, rain, surge, and flooding affected different parts of the property and when the damage occurred.

Challenge improper allocation
We respond when an insurer shifts damage to another policy, applies the wrong deductible, or leaves a documented portion of the loss unresolved.

Pursue recovery across the claims
We negotiate with the involved carriers and assess litigation when coordinated claim handling does not produce the coverage required by the policies.

Questions
Hurricane damage claim FAQs
The following information is general. FDZ Law can review the policies, deductibles, causation evidence, and payments involved in a specific hurricane claim.
Does it matter if hurricane damage is attributed to storm surge instead of wind?

Yes. The assigned cause can determine which policy or exclusion applies and may materially affect payment. Wind-versus-water disputes often require a careful review of the event sequence, damage pattern, policies, and expert evidence.
How is a hurricane deductible generally calculated?
A hurricane deductible is often stated as a percentage of the dwelling coverage limit rather than a flat amount, although policies vary. The triggering event, percentage, coverage base, and calculation should all match the policy terms.
Why might part of my loss remain unpaid with both homeowners and flood insurance?
Homeowners and flood policies may apply different causes, exclusions, deductibles, limits, and valuation rules, which can leave disputed gaps. FDZ Law can review both policies and the carriers' allocations to identify areas that may require further evaluation.

Types of claims we handle
Every type of property loss, covered.
We handle every type of covered building and personal property loss that may affect your home or business.


Ready to start the process?
Share the basic details of your situation. The firm will review the information and explain the appropriate next steps.




