

Insurance Claims
Water Damage Insurance Claims
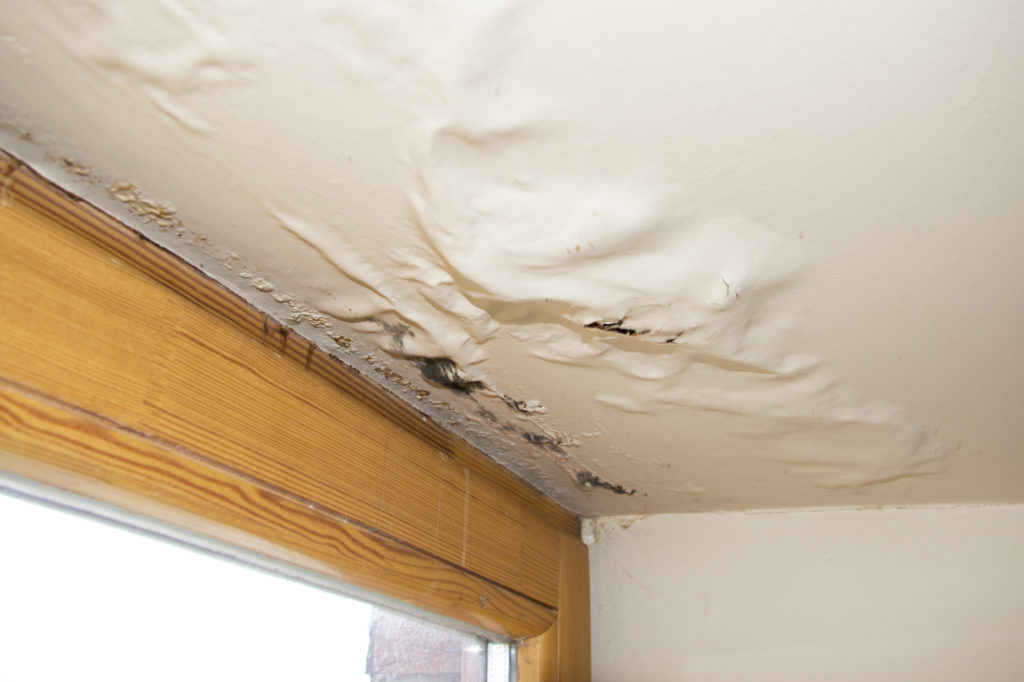
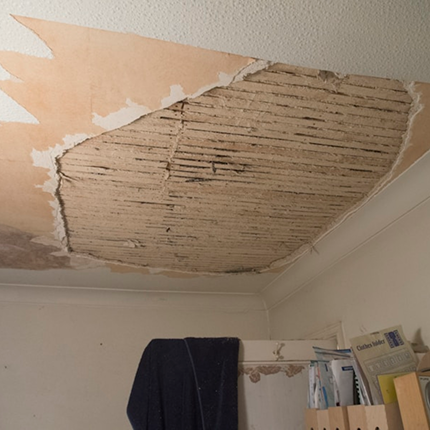
A burst pipe, appliance failure, roof opening, or overflow can damage finishes, structural materials, and personal property within hours. Carriers often dispute whether the event was sudden, how far the water traveled, and which repairs are covered.



The situation
Why water damage claims are often reduced or denied
Insurers frequently point to long-term seepage, maintenance, or an earlier moisture condition when denying a water loss. They may also limit the investigation to visible damage while excluding hidden moisture, demolition, drying, mold, or repairs needed to reach damaged components.

Common obstacles
Why these claims are often disputed
Insurance companies employ experienced adjusters whose role is to limit payouts. Knowing where disputes typically arise gives policyholders a real advantage.


Examine the coverage decision
FDZ Law compares the policy language with the reported cause, inspection findings, and denial or payment explanation.

Establish the source and timeline
We organize records that show when the event occurred, how the water entered, and why the evidence supports a sudden covered loss.

Document hidden and related damage
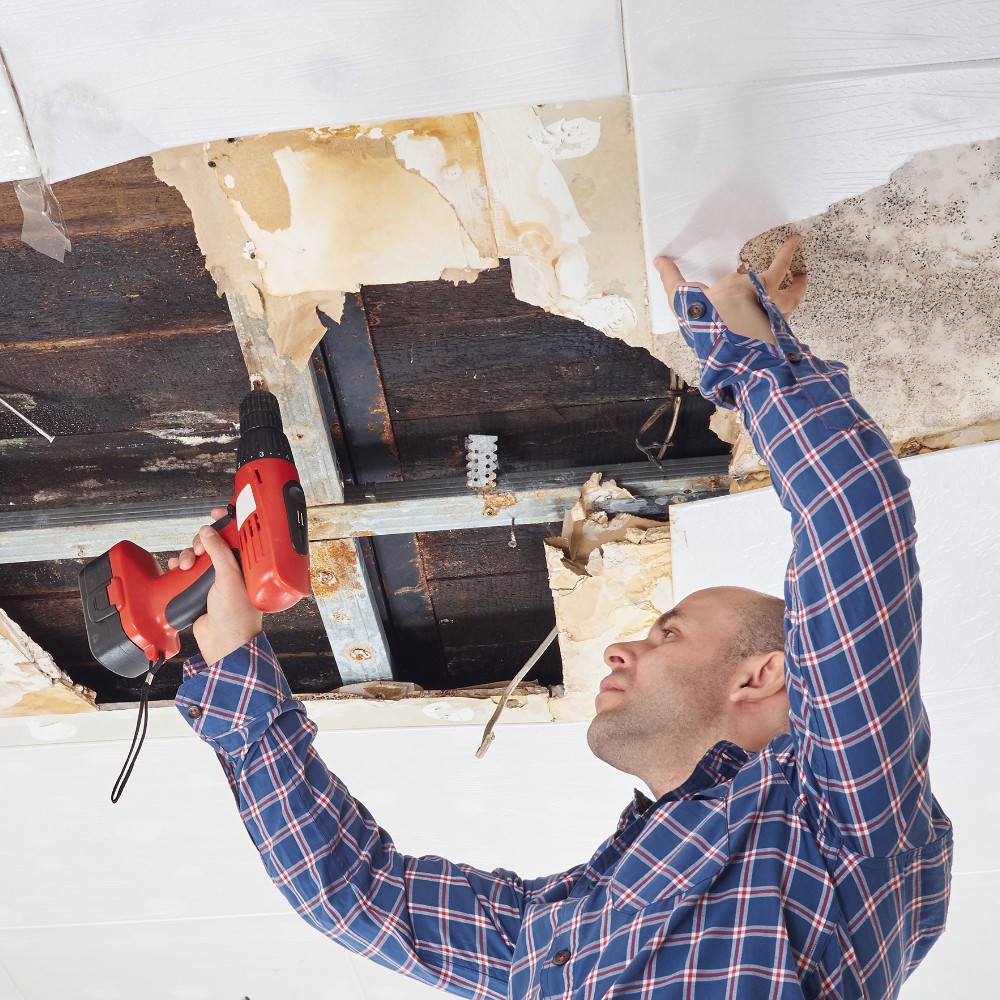
We help present the full repair scope, including concealed moisture, access work, drying, damaged contents, and resulting conditions when applicable.

Challenge an incomplete claim payment
We negotiate disputed coverage and valuation issues and assess legal action when the carrier does not properly address the covered loss.

Questions
Water damage claim FAQs
The information below is general. FDZ Law can assess how the policy language and cause of loss apply to an individual water claim.
How can I respond when the insurer calls the damage gradual?

A gradual-damage conclusion may be based on a limited inspection or incomplete history. Photographs, repair records, moisture data, and an appropriate expert assessment may help show whether the damage resulted from a sudden and accidental event.
Can mold be covered when it develops after a covered water loss?
Possibly. Mold coverage depends on the policy, including any exclusion, sublimit, or endorsement. Evidence connecting the mold to a covered water event may be important, and FDZ Law can review how the insurer applied the relevant provisions.
How can I dispute a repair estimate that appears too low?
You may be able to challenge the carrier's estimate with photographs, measurements, contractor pricing, expert findings, and an itemized comparison of omitted work. FDZ Law can review the scope and explain which disputed items may require further support.

Types of claims we handle
Every type of property loss, covered.
We handle every type of covered building and personal property loss that may affect your home or business.


Ready to start the process?
Share the basic details of your situation. The firm will review the information and explain the appropriate next steps.




