

Insurance Claims
Windstorm Damage Insurance Claims
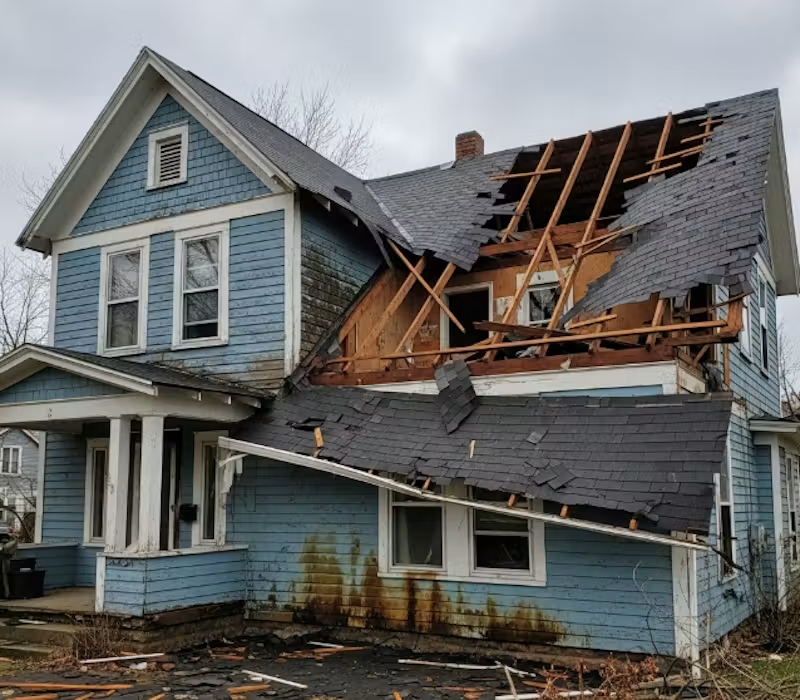
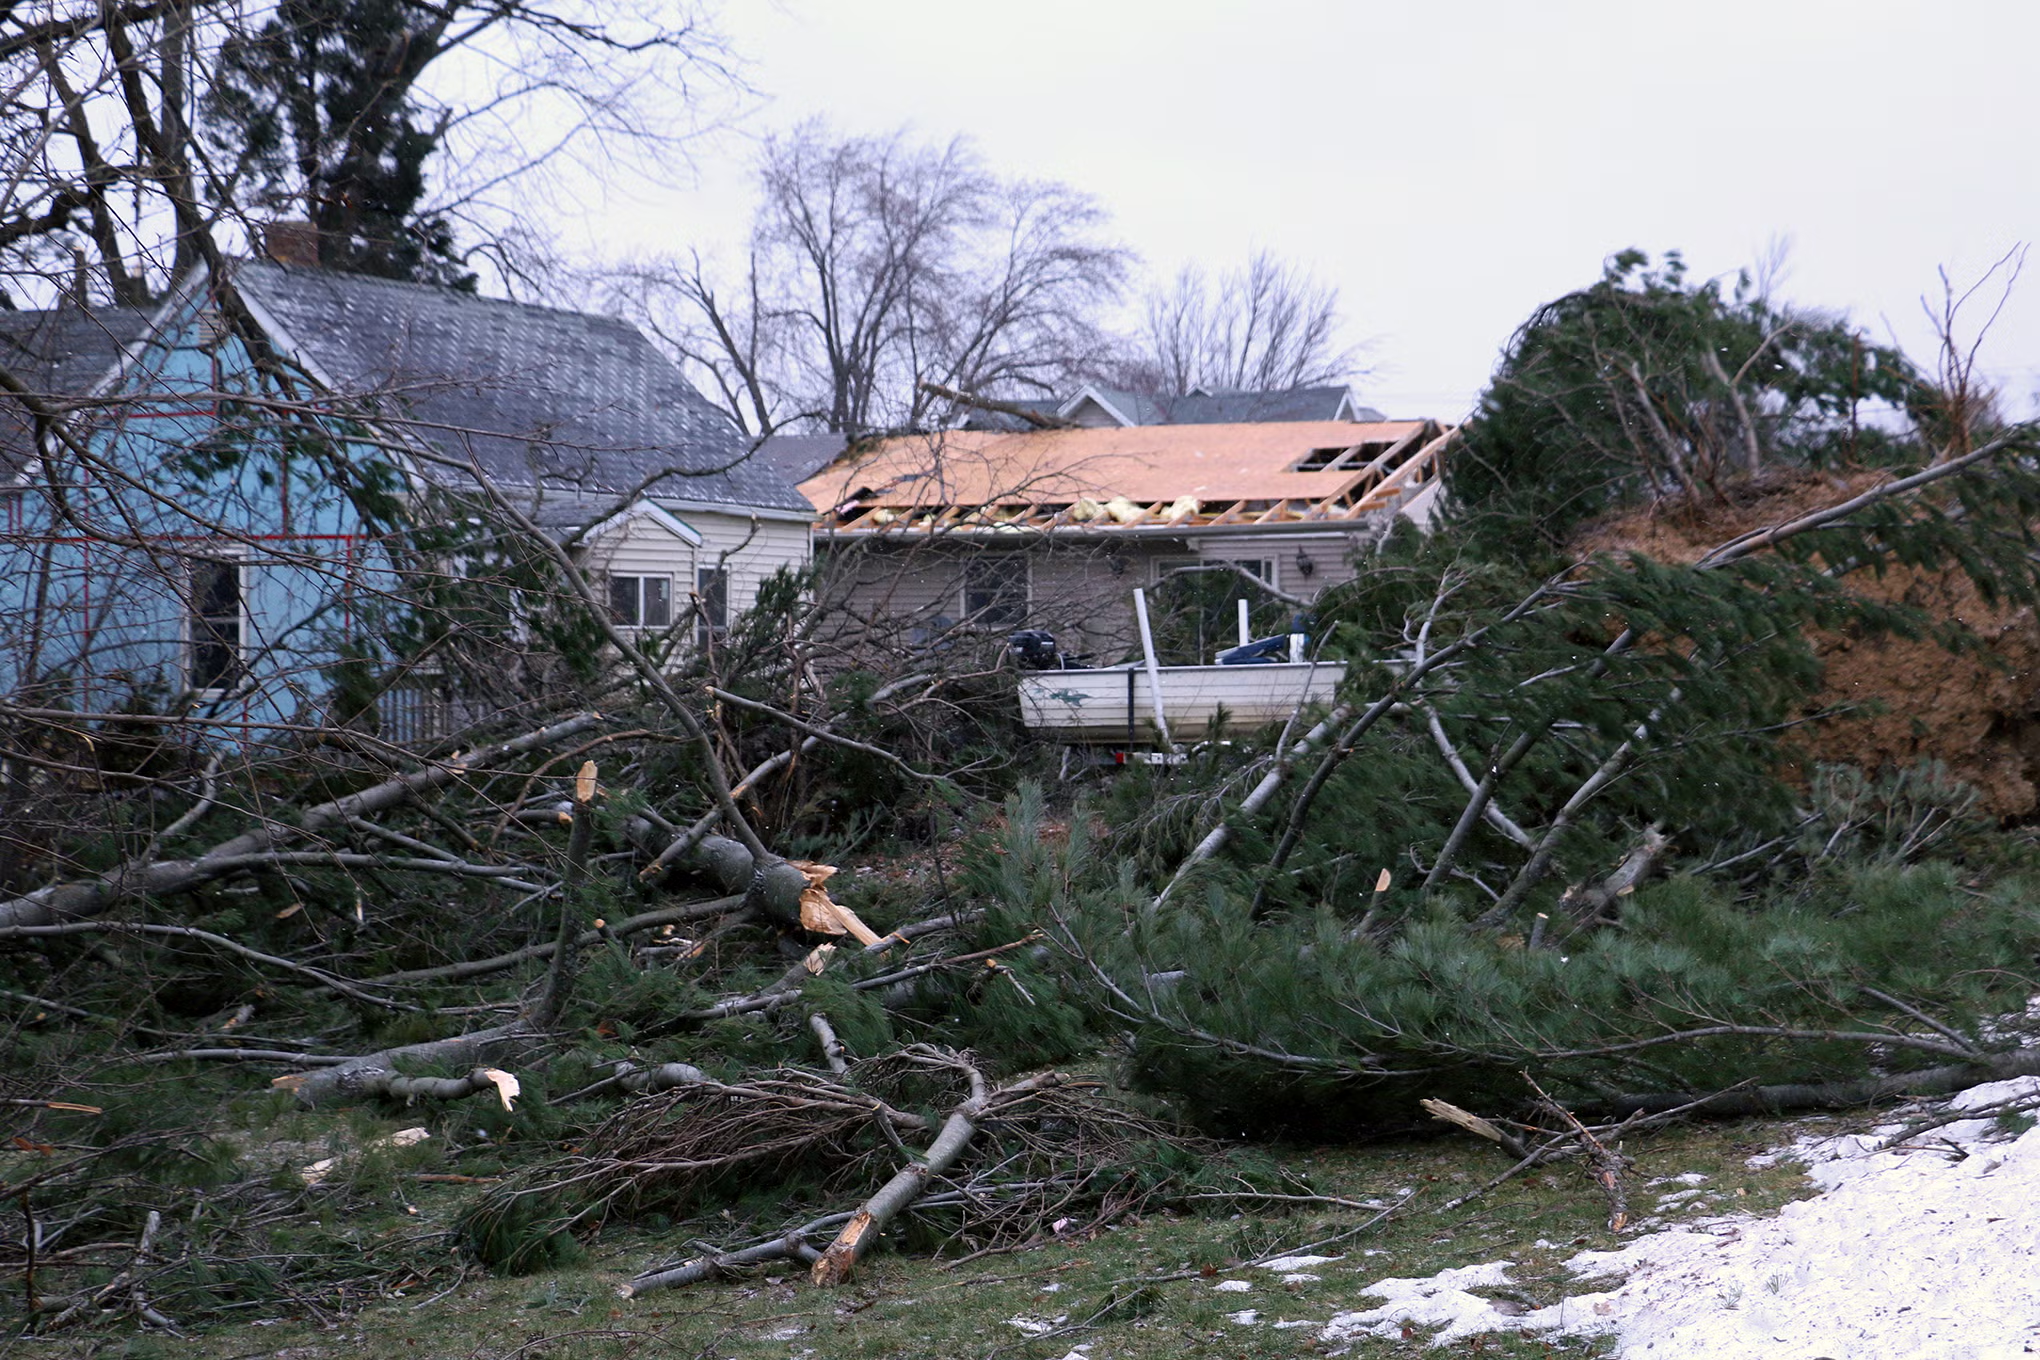
High winds can lift roofing, break openings, damage siding, and affect detached structures. Insurers may attribute the damage to aging materials, apply a separate wind deductible, or approve only selected portions of the claim.



The situation
How windstorm claim disputes develop
The central disagreement is often causation: whether the storm created the damage or merely revealed an existing condition. Carriers may also apply exclusions, percentage deductibles, or narrow repair scopes that leave related interior, exterior, and detached-structure damage unpaid.

Common obstacles
Why these claims are often disputed
Insurance companies employ experienced adjusters whose role is to limit payouts. Knowing where disputes typically arise gives policyholders a real advantage.


Analyze causation and coverage
FDZ Law reviews the policy, storm information, inspection findings, and claim correspondence to evaluate the carrier's cause-of-loss position.

Connect the storm to the damage
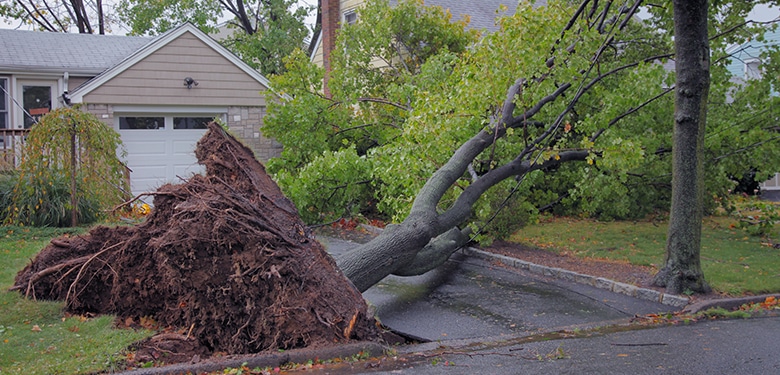
We assemble photographs, repair records, weather information, and expert evidence that document the property's condition after the wind event.

Review deductibles and exclusions
We examine whether a windstorm deductible, maintenance provision, or exclusion was calculated and applied consistently with the policy.

Pursue unresolved covered losses
We negotiate partial denials and underpayments and evaluate litigation when the carrier's position remains unsupported.

Questions
Windstorm claim FAQs
These answers are for general guidance. FDZ Law can evaluate the policy, storm evidence, and disputed portions of an individual wind claim.
How does a windstorm deductible affect my payment?

A windstorm deductible reduces the net amount paid, but the insurer must use the correct trigger, percentage or dollar amount, and calculation base under the policy. FDZ Law can review whether the deductible was applied as written.
How can I show that my roof damage was caused by the storm?
Pre-loss photographs, maintenance and inspection records, immediate post-storm images, weather information, and expert findings may help distinguish new storm damage from earlier wear or deterioration. FDZ Law can assess the insurer's pre-existing-condition position.
Can the insurer approve part of a wind claim but deny my fence or detached garage?
Coverage can differ by property component, structure, limit, and cause of damage. A partial denial may warrant review when the fence or detached garage was damaged in the same wind event. FDZ Law can compare the denial with the policy and supporting evidence.

Types of claims we handle
Every type of property loss, covered.
We handle every type of covered building and personal property loss that may affect your home or business.


Ready to start the process?
Share the basic details of your situation. The firm will review the information and explain the appropriate next steps.




